
How much cash should you keep?
Inspired by a number of reader questions over the years, I thought I would chime in on this subject: how much cash should you keep including our plans when it comes to cash.
I’ve updated this original post from 2022 to demonstrate how our thinking has changed over the years as we plan for retirement spending as soon as 2026.
Reader questions in fall 2022 (adapted only slightly for the post)
Hi Mark,
In a recent weekend reading the following quote caught my eye: “The only time you should be worried about a correction is if you need the money within the next five years and haven’t made an appropriate plan to access the cash.”
What did you mean by that?
I am 68 years old and my portfolio has done quite well during the last year. I feel however there is going to be a major market correction (cause unknown at this point) and would like to put a plan in place to access the recent growth (still within my RRSP). I have raised this with my financial advisor who says to stay invested (modest growth profile) however I don’t feel I have a plan in place that addresses my needs in the next 1-5 years.
Thoughts?
Overall I am happy with my financial advisor’s advice but feel that changes are needed.
Related to the email above…
Hi Mark!
You might be on holidays – and if so, I hope you ignore this email until your return. (Mark – I didn’t!)
I just wanted to check in to see if you know when you might cover this. In particular I’m keen on better understanding a “plan” to access the recent growth I’ve had in my RRSP as I don’t think I have the timeline to go through another 2008 type of recovery to my portfolio. I am thinking about it as a “fold and hold” strategy. I think I would sleep better although my advisor wants me to stay fully invested – however I think this might be to his advantage rather than mine.
And another one…
Mark,
I know you have talked about having a cash fund to cover 1 years’ worth of expenses. At the same time you mention the importance of being invested. Is that conflicting a bit?
What I mean is, our rule of thumb is $30k invested, creates $1k of dividend income. So you can quickly figure out how much you need invested to cover your yearly costs.
Back in our student days, we tried to keep a cash balance of $500. That slowly went up to $1k. Now, years later, that fund tends to float around the $5,000 mark. Having two kids, it is amazing how much money flows in and out of the chequing account each month! Stunning really, if you went back in time and told your 10 year old self how much money you would have filter through your hands each month. Damn!
I can see the rationale for wanting a cash safety net, but when do you build it up? And by the time you might build one, you should at that point already have a solid stream of income that covers your expenses. See my rule of thumb above.
Once you punch through to the double coma world, or double dot if you’re European, you might find you don’t need as much cash on hand since the portfolio delivers everything you readily need.
The monthly income growth via dripping takes a life of its own…
I know some of your readers think this way already, which is ideal, since the best thing we did was track income from the beginning. Yes, the capital amount is nice to observe, but that isn’t what we plan to have paying the bills.
The summary: when the income from your portfolio delivers what you need and then some you don’t need as much cash on hand as you think.
Great stuff readers!
How much cash should you keep?
There are a few things to unpack above so I’ll try and tackle answers to those questions below.
First, good on any reader to take more control over their money.
Here’s my take on how much cash should you keep!
1. In retirement, I think any money you absolutely need/will absolutely depend on in the next 1-2 years should likely be in cash or some form of fixed income.
While I have always believed cashflow is king keeping some cash on hand is good too. 🙂
That could apply for your asset accumulation years too.
Example: you’re saving for a house (i.e., you really need that down payment). Or, if you have any other major spending items coming up (e.g., you need cash for a car) then your money should not be in stocks.
Your money should not be in any near-term volatile investment.
That’s just me.
Here is my thesis:
“Any money you absolutely need within the next 1-2 years should be maintained in cash/cash equivalents for near-term spending.” – My Own Advisor.
I personally believe in cash/cash equivalents to navigate at least a 12-month major stock market calamity should be your base in retirement.
I will try and eat my own cooking and do that.
I remind myself of this graphic as well when it comes to corrections:
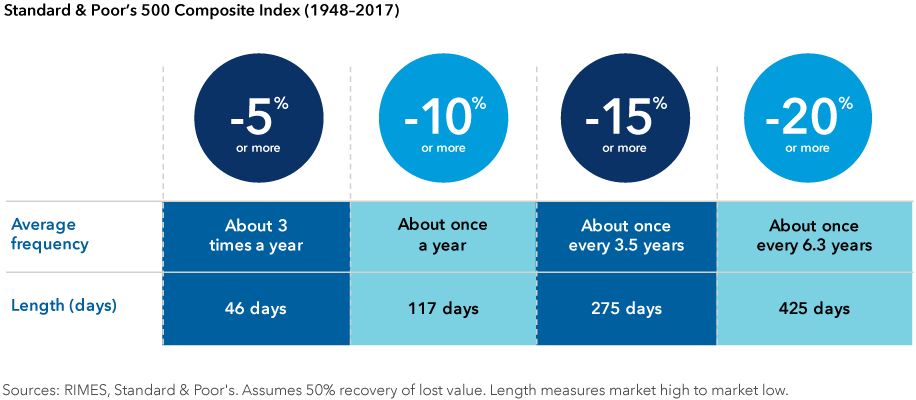
So, our plan is to be ready for this at all times: given a stock market correction happens at least once every two years, triggering 10% or more declines, we will always keep cash/cash equivalents in our accounts for near-term spending.
Cash should be there especially when you think you won’t need it. That brings me to this.
2. I think most people should have an emergency fund at any age.
Other than a few occasions where we’ve dipped into this account, we strive to keep emergency cash on hand / which is our emergency fund while working full-time at this amount.
We’ve done that for about a decade now.
Sadly, $hit happens.
I believe the last thing you want in any financial emergency for you is to go into more debt (and/or the stress of taking on more debt).
How much cash should we keep?
Passionate readers of this site will know we are approaching semi-retirement in the coming years.
You can read about our “bucket approach” related to earning retirement income here.
While some cash will be in a high-interest savings account for immediate liquidity, registered investments will also have some cash too. Increasingly so for any registered withdrawals in retirement.
In The Psychology of Money, author Morgan Housel shared:
“The most important part of every plan is planning on your plan not going according to plan.”
How true.
Housel went on to write in his book:
“The biggest single point of failure with money is a sole reliance on a paycheck to fund short-term spending needs, with no savings to create a gap between what you think your expenses are and what they might be in the future.”
Read more: The Psychology of Money.
When it comes to semi-retirement spending or early retirement spending in the coming years, I believe the worst thing you can likely do in any potential market meltdown is sell lots of equities.
Some folks might argue the “4% rule” is a good rule of thumb for any retirement drawdown plan. I believe that rule is a decent starting point but hardly a rule to follow explicity.
Here is an early retiree that totally ignored the 4% rule.
Here are some other posts on my site to help you and others out on that subject:
How to use Variable Percentage Withdrawal (VPW).
I know some readers on this site use the VPW approach to drawdown their portfolio. I will likely use some form of this myself.
Is our 1-years’ worth in cash too much?
Reader: “I know you have talked about having a cash fund to cover 1 years’ worth of expenses. At the same time you mention the importance of being invested. Is that conflicting a bit?”
Great question but I don’t see it that way.
At the time of this original post (2022), I sleep better at night with cash/cash equivalents on hand.
As of summer 2022, here was our cash position:
- Savings / Emergency Fund = maintain $10k via a Higher Interest Savings Account (HISA).
- Investment accounts = >$10k inside our RRSPs for strategic buys during the year.
- Corporation = > $30k maintained inside my corporation account for future withdrawals.
Now, in 2025, as we consider full retirement in 2026, our cash/cash equivalents position has evolved.
Recall:
“Any money you absolutely need within the next 1-2 years should be maintained in cash/cash equivalents for near-term spending.” – My Own Advisor.
Things look like this at the time of this post planning for retirement in 2026:
- Savings / Emergency Fund = always maintain standing $10k via a Higher Interest Savings Account (HISA).
- Investment accounts = >$30k inside our RRSPs specifically for future withdrawals.
- Corporation = > $100k maintained inside my corporation account for future withdrawals.
When should I build up my cash wedge?
Reader: “I can see the rationale for wanting a cash safety net, but when do you build it up? And by the time you might build one, you should at that point already have a solid stream of income that covers your expenses.”
Honestly, hard to say. I hope you are correct of course!
We believe having multiple income streams in semi-retirement will provide redundancy. We won’t be reliant on any singular income stream to fund our needs and wants.
Again, a reminder:
“The biggest single point of failure with money is a sole reliance on a paycheck to fund short-term spending needs, with no savings to create a gap between what you think your expenses are and what they might be in the future.”
For any retiree, I believe when you’re about 3-years away from semi-retirement or seeking full retirement is when you need to consider your cash wedge and therefore bolstering your emergency fund.
For us, the work started in late-2022.
This was about three years or so prior to any potential retirement since I posted this article a few years ago prior to this 2025 update.
Reader: I have found “the monthly income growth via dripping takes a life of its own”.
Indeed good reader!
It’s quite remarkable to see our own portfolio on autopilot.
In 2025, we continue to have dozens of stocks and ETFs DRIPping every month and quarter.
How much cash should you keep summary
Our cash journey might be different than yours!
Our decision:
2022: we’ve decided a few years ago to hold a mininum $50,000 in cash savings to plan for semi-retirement with. Everything else was invested in stocks/equities.
2025: we’re now holding at least double that value to start retirement spending with in 2026.
Your personal finance journey will be forever personal.
We believe spending from cash/cash equivalents in retirement, first, will allow markets to market.
Holding cash/cash equivalents will buffer us from any stock market declines for at least a year while we keep the rest of the portfolio invested for income and growth.
Your mileage may vary.
Readers, what do you make of having any sort of cash wedge or higher cash savings position in semi-retirement or retirement?
How much cash do you intend to keep? Why?
Happy to read and learn about your cash approach or feedback on mine below! Thanks for your readership.

Hi Mark: Everything is approximate but about $242k in dividends will roll into the cash account along with new units that build up in the back ended mutual fund and the money market mutual fund. At home about 20k from stocks in the security box. There are other assets also. I will be more exact next March and April I’m afraid. Since Mr. Market won’t let me participate because it is so high then the dividends will keep on rolling in and just build. When the market drops and prices are right than I will buy more shares and increase the dividends rolling in. More tax to pay but that is the price of getting ahead. Which reminds me that a very painful transaction occurs tomorrow. Even though the dividends are constant they still grind higher. I can pretty much count on National Bank increasing the dividend on 1 Feb./ 26 by $80.00 and then another $80.00 on the 1 Aug./ 26 and Enbridge will increase its dividend by $577.50 on 1 Mar./ 26. All flow to the cash account and if needed for every day living will then flow to the checking account. The shares at home are the residual of the shares not called in or sold and then moved to Waterhouse. They give me some cash at home.
That’s incredible. About x4 higher than me. 🙂
Do you just let your dividends roll-in as you put it?
No dividend revinestment at this time?
As you mentioned, that is our plan with the divis = all cashflow in the coming years for living expenses…hopefully growing over time to cover living expenses.
I assume that has been your experience. 🙂
Mark
It used to be 100% equity but now that I am planning to retire within 5 years our allocation has changed to 70/30.
I would never buy FI with new inflows if the allocation is 65/35. These days as the market is strong, money tends to go into FI but we’ve had some stock-buying spells this year in spring and summer.
A portion of 30% is cash/cash equivalents. We tend to keep it in $100K-$200K range to cover emergencies. I would never count on future dividends for emergency cash.
Good stuff, Mordko. Earlier this year was a good time to buy equities. Now, seems folks can “trim” a bit as needed and raise cash/cash equivalents or have more fixed income on hand given where markets are at.
Same: “I would never count on future dividends for emergency cash.”
I figure we’ll always have an emergency cash fund of $10k (had in place for well over a decade now) and then beyond that, keep another $50k as a standing cash wedge. If/when cashflow from the portfolio (via dividends + ETF distributions) is > expenses, then I know if major market calamity ensues we’ll simply scale back some discretionary spending for a period of time as needed.
Our base expenses in retirement as of 2026 should be close to $4,500 per month without any travel or any entertainment spending.
We have already exceeded that from a few key accounts:
https://www.myownadvisor.ca/august-2025-dividend-income-update/
By the end of the year, we night be closer to hitting $55k per year and that excludes other assets we have. So, getting there is what I am saying!
Thanks for your comment,
Mark
Hi Mark: I have been investing since I first started working in ’69. My dad got into it and found success so everyone had to get in it but I was still going to school so I sort of took a course in it from dad. There were interesting things going on then too. There was a company in the ’60’s in the mining industry called Winfall Resources which was all the rage but in the end turned out to be a fraud. The owner ended up in jail. This company was Bre-X Minerals before Bre-X Minerals was Bre-X Minerals. When I got laid off in Jan./’92 did I sit back and rest or did I keep on investing. My situation was different than most as I’m single and already knew how to look after money. I had $400k and because of as now the market was pulled higher by then the Dot Com Bubble so the 2nd week of Sept. of ’97 I went over the 1 mil mark. All along I kept on investing and stocks kept on splitting and the dividends kept on growing. I bowled, curled, golfed and lived. I wasn’t going on worldly trips then but I did most things and any big purchases (cars) the stock market paid for them. Most of my stocks have been Blue Chip companies but the odd time I have played with my money. One time was when I was working in the basement of the GE with all its amenities you know like the thick cement wall at my back, the bare cement floor, the sunlight streaming through the window above my head while sitting behind an ammonia belching white print machine while the heat and water pipes run above my head but there one perk and that was on the far side of the basement were the printers and each week they printed the Works News. One story was that GE was making a ball mill for Great Lakes Nickel. It looked legit and the company was on the stock page and was only $.70 so I took a gamble and bought 150 shares. It promptly dropped to $.35 and I thought Oh No but it rose to $1.50 and then sank to $1.15 at which point I sold it as I had made a little gain. Most of my stocks now are solid dividend paying companies which raise their dividends each year. In the last going on 34 years I have kept investing and the dividends have kept increasing and I have no plans to stop. Yes my expenses were low but if I can do it most people who know about the market should be able to do it to. That is the beauty of the power of compounding.
Great background!!
Ya, many of our stocks are established blue chippers as well….but I do own some ETFs for extra diversification.
What do you think or know is your total cashflow from the portfolio – how much income does the portfolio generate?
Cheers,
Mark
Hi Mark: When it comes to retirement some wonder if I have enough to live on but don’t forget the government pensions and work pensions that can be added on to your portfolio as these will take some of the sting out of not receiving your work check. Like in the movies that phrase “your assignment should you accept it is to take that potential $70k and grow it to $100k and then grow that to $125k and then $150k etc. It is a life long journey and if you stop to live off your portfolio your portfolio will get smaller and with inflation things will get more expensive so don’t stop. As for the journey I really enjoy it. I know you have your series called The and Now but have you ever reminisced on were things were and were they are now. Take TRP as back in the ’70’s they had just a couple of pipelines and now they dip into most gas pools in North America. And speaking of TRP do you remember when it was owned by BCE and why did Bell Canada become BCE in ’83. Maybe because not only did they have Bell Canada but also TRP, CTV, National Pagette which morphed into Bell Mobile, Bell Emergis, Bell Canada International, Nortel Networks and Teleglobe. Today it has been simplified to make things easier to understand but I find this history interesting. I was never in Oil’s but in the ’70’s and ’80’s there were some very prominent energy companies that are no longer on the board. Were did they go? So I googled it and was surprised to see where they ended up and which companies took them over. I find this business history interesting and makes owning the stocks I own more compelling than just the money aspect of it although the money aspect isn’t bad either but the companies history adds something to the stock.
Thanks for your detailed comment.
Agreed, once we stop working, life could get more expensive but my projections show we are “OK” with 5% sustained returns with 3% sustained inflation = 2% real returns if we start spending about $85k or so per year starting in 2026. Our target spend is $75k next year with 10% buffer.
That means our spending by even age 55 should be fine closer to $90k per year.
I do think back to those companies and various takeovers. How long have you been investing overall? Since the 1970s?
Cheers,
Mark
Hi Mark: How much cash should you have? Well as you aptly say it depends. At the moment the market is telling me that I can’t buy anything because everything is so high so the dividends from my portfolio will just have to go into the cash account and build. There is a lot but I have yet to meet the person who complains that they have too much cash. When the cycle turns as it will then I will put that cash to work. While the market goes up and down the dividend cash flow remains constant. I’ve come to think of the dividends as like another pension check and its nice to see each one roll in. No big plan here. Bills come in, Bills get paid, more dividends roll in and now I’m back were I started if not ahead and the cycle starts all over again. Someone asked me when do I stop and I said what do you mean. She said well there comes a point were you have enough and I said you never have enough as dividend investing is a life long journey and more money is better than not enough.
Well, we’re 90% stocks/equities (your favourites like ENB, BN, etc.) and 10% cash/cash equivalents.
The market is expensive these days…not buying lots although I continue invest here and there…
Same: “I’ve come to think of the dividends as like another pension check and its nice to see each one roll in.”
Ideally, we’re beyond our $53k per year and hopefully closer to $70k per year in a few months once other portfolio changes are made, which I will post here.
https://www.myownadvisor.ca/august-2025-dividend-income-update/
I suspect you like the journey = no reason to stop. 🙂
Mark
I think it depends on how your income is structured (pre vs. post benefits) for us post includes OAS/CPP/DBP/RRIF/TFSA and projects income of >100K py which is roughly split 50/50 between “guaranteed/at risk”. We intend to live off $80K net the rest functions as emergency/opportunity/flex/savings/fun fund.
Worst case we only need to cover $25-$30K of at risk income py. Extremely unlikely I do not foresee a scenario where all our investment income stops. A 10-15% correction barely shows up on the income side at 20+% you start to see some impacts a 40% correction does hurt yes but it’s not a 1:1 ratio to income. I’d consider a max 30% income reduction as a could happen scenario for which we aim to hold enough cash + fixed income to cover 2+ years of income shortages in our RRIF’s and TFSAs (~$30K currently). This is on top of our ~$20K income buffer I think this is very much overkill as meaningful market recovery is typically a lot shorter than peak-troth but as always time will tell no point losing sleep over this.
If your mix is different (i.e. pre benefit or more growth vs income focused) than you’d want a higher number. For income investors holding 1Y makes sense in most cases. I personally wouldn’t do more unless I had a sense of purpose (big travel, wedding, reno..) the difference of having i.e. 50K returning 2-3% vs 8% pays for half of your trip to St Lucia. I would hate to have to explain to the Mrs. she can’t come.
Great stuff, Ben.
Very close here – our desired/planned spend in 2026 is about $75k per year (after-tax of course) and we have buffer to about $84k.
We can live off that without CPP or OAS income streams yet…we will drawdown our portfolio over a few decades instead.
Potentially this is where we are doing something different – I will spend from cash/cash savings first and leave assets alone vs. maintain/hold ~2+ years of cash + fixed income.
The reason being, while we are spending that cash, dividends and distributions should happen such that we have cash ready in the coming years for further spending.
Is that the same approach as you or are you always keeping that 2+ years’ worth in cash/fixed income as part of your asset allocation?
I would agree in that given my approach is a blend of income and growth, I need a bit more buffer since growth may or may not happen.
I report we earn about $53k per year in income from key accounts at this point but that largely ignores my growth story. 🙂
https://www.myownadvisor.ca/how-much-cash-should-you-keep/
We’ll see how the market behaves moving forward, I have my doubts!?
Mark
PS. St. Lucia sounds lovely…
Hey Mark,
Re “Is that the same approach as you or are you always keeping that 2+ years’ worth in cash/fixed income as part of your asset allocation?”
Nothing is ever set in stone but for now if we need ~$30K and our max income shortfall is covered for 2+ years that sounds like a reasonable default to me. Btw it is bigger now than it has ever been in part due to how your outlined your approach. If we would be living of our RRIFs/TFSAs exclusively it would be quite a bit higher.
We hold some cash and money mart but mostly it’s short term bonds and high quality corporate credit (AAA CLO’s) so not strictly speaking “Cash” we get almost 5% in return with little risk. I would likely always have a low risk allocation in the $20-$30K range even just have on hand should we get a major correction. Remember QQQ usually is up >50% the year following a big crash.
In future our expenses will change, mostly down I hope, we might use some of that cash and income surplus to invest in our home instead. Doing some legwork on Solar at the moment that could make electricity a low/no cost item or likely an income stream in time. In all that could yield >$100K in cost avoidance/income over the lifespan of the system (net of cost). You can get ahead financially outside of stock and bonds.
Ben
Good stuff.
For sure, nothing carved in stone.
I got out of all QQQ near the top this past summer, we’ll see if it climbs higher – it probably will (maybe some FOMO??) but I have thousands of XAW and I use that for diversification beyond Canada and that includes 60% U.S. holdings – so it’s not like I’m losing out on tech.
As I approach 2026, cashflow from the portfolio is VERY important to me. Growth is good, for sure, but you never know where that is going to come from, how much, and when. I would say >50% or so of my portfolio is designed for income and likely always will be.
Indeed, you can: “You can get ahead financially outside of stock and bonds.”
Cheers,
Mark
Too many variables and too complicated to come up with a ‘fits all’ plan. People would have to consider the likely possibilities of needing extra funds and what amount of $$ that might entail. Makes my head spin when I go over all the “what ifs” we took into account. Many might consider our amount to be excessive.
I’d certainly advocate for having some level of cash on hand, what that amount might be is up to each person/family.
Well said.
I know some folks that are 100% equities. Some comment here. They don’t feel they need much cash at all because dividends and distributions + pensions, etc. cover all expenses and then some. So, to them, why bother (??) with a large emergency fund? That works for them. Not for me/us.
For us, younger, more risk, I feel it’s different – we need a margin of safety. We figure having all 2026 spending ready to roll is a great start for us. We’re 90% invested in the stock market/in equities otherwise.
I appreciate your comments,
Mark
“That works for them. Not for me/us.”
Same here. Once I explored the costs of a major house renovation, supplementary/privately funded home/nurse care, possible handi-van acquisition (or expense to hire same) as well as other items not normally considered, it added up to a possible need for significant funds. In hindsight, with the market doing what it did, investing would have grown the funds to a greater degree. But when the decision was made, no one could have known that. Having substantial cash ready, when/if needed, without having to worry about future market conditions was a great stress reliever.
Amen: “Having substantial cash ready, when/if needed, without having to worry about future market conditions was a great stress reliever.”
🙂
Yes, I am one of those that don’t need a cash wedge. First we have CPP, OAS, and a small pension. In a real emergency that would cover basic living expenses. Minimum withdrawals (all dividends) from RRIF’s covers everything else. We are not touching TFSA’s at all. Dividends overall should be up 8% over last year, total portfolio growth year to date is 16%. Growth can change anytime, but dividends for now remain steady. All our extra cash now goes to private lending at higher interest rates, 11 – 14%. These are not liquid investments, But this money is not needed and I can’t just have it sit on the sideline. Not selling anything, and just adding more shares to TFSA’s with the dividends. But that’s just me, everyone has their plans.
We are hopefully still a ways away from supplementary/privately funded home/nurse care, but that should also be covered by dividends/interest when the time comes.
I was hoping to hear from you on this….
First, excellent: CPP + OAS + small pension seems to cover most expenses.
Second, I hear ya in that you are not touching TFSAs. We see those are larger emergency funds for our early retirement years.
Third, finally, I also hope to avoid selling any capital/assets in the coming years but we will sell some stuff in registered accounts for sure in the coming 20 years, otherwise we won’t be living “our best lives” while we can.
I appreicate your comment!
Mark
Timely refresh for me. Still no contract, but the number of opportunities is rising. I’m optimistic.
In the meantime, we are still withdrawing almost all dividends from the non-reg account to meet our spending needs. Therefore, not dripping, and not adding any new funds.
My cash flow plan was to stop dripping six months before we both retired and build up our cash wedge that way. Currently, this is not an option.
My thinking is if I start some new contract work I will use that income to a) focus on pre-paying our mortgage (currently less than $70k) and turn the DRIP back on in the non-reg, and then proceed with the original plan. Turn the DRIP off six months prior to “actual” retirement.
We do have about six months of variable spending saved up, while my wife’s income covers all the fixed expenses.
It’s looking more like my wife might retire a few months prior to a full pension, while the contract work I might get would be much longer term. I could see working out to 2028 potentially, if I’m enjoying it.
If the contract work doesn’t materialize I’ll be looking for alternative employment that will likely still require augmentation from non-reg dividends.
PADI is now $75.3k across all accounts. It’s unlikely that we will hit my arbitrary target of $84k by retirement.
My planning tells me is that this will have a modest to medium impact on variable spending in retirement, including foregoing one or two years of snowbirding (we won’t set foot in the States for the time being anyway).
For now, we are making ends meet and the desire to retire sooner, rather than later, is rising. Just have to find a way to make it all work.
Your wife is still working so you’re in great shape, James.
Kill the debt and then enjoy your life. 🙂
Smart: but I’m biased since I plan to live off dividends from non-regs x2 here and not touch any capital near-term. All dividends are paid as cash for spending/expenses like condo fees, property taxes here in Ottawa, home and car insurance, etc. every month.
As I referenced in my post, DRIPs are largely turned “OFF” for cashflow. Just simple that way for us.
Kill the debt as much as you can and live your life – it’s short and precious and I’ve seen it first hand this year with my dad’s ill-health.
🙂
Mark
I think it is important to highlight that if you choose to have cash available, and are making mandatory withdrawals from RIF or LIFs, that some cash( or cash equivalent) be held inside the RIF or LIFs. That way you don’t have to sell equities to meet the withdrawal minimums.
Very great point. I’m not there yet with my RRIF or LIF mins. but I do know in supporting my parents with their withdrawal strategy, this has worked very well.
They tend to have cash/cash equivalents ready about a year or so in advance of when they need to meet RRIF min. withdrawal retirements so there is not any urgency to sell anything on a whim. They have their RRIF min. withdrawals set up in Jan. every year to take advantage of TFSA room and/or plan for annual tax filing.
Thoughts?
Mark
We also take out more than the minimum so we can top up to bracket and fully fund our TFSAs. If the markets tank, our minimum RIF and LIF withdrawals would be immediately reinvested back into our TFSAs. The cash equivalents would provide our income needs until things turn around. We calculated about three years worth to cover worst case scenario.
I know other retirees that do the same thing, Carl. Very wise – keep maxing out TFSA.
We hope to fund our TFSAs again in 2026 and are likely to buy more XAW.
Mark
Commenting on this despite it being a few years old but you referenced it in your latest newsletter. We are keeping at least a year of expenses in cash in our retirement and topping that up as necessary. The good thing is, for now at least, we are getting 4% interest on that cash from EQ. This isn’t a bad situation as at least the cash is protected from inflation in the short term and might be slightly ahead.
I lime having the buffer which gives you peace of mind that you could weather at least one bad year and time to adjust if a longer term downturn was in play.
I appreciate the comment, Bill. I like to go back to what I write about from time-to-time on this site to see if what I mentioned was right/accurate or simply a passing/fleeting thought at point in time. 🙂
Getting 4% or so, even 3.5%+ for idle-cash is smart I believe. I’m doing the same.
It is my hope we will have summer 2025 and the entire year of 2026 spending needs for semi-retirement in cash/cash equivalents in the coming 6 months or so. We’ll see?!
Have a great weekend,
Mark
I’m going to call you on this:
Those folks that have not saved over 20 years like I have, diligently, certainly won’t have this portfolio value. It does take time and effort!
Not everyone has the income to save this much money either! Its not all about time and effort!
Call out away, Christina!
Time, effort, living below your means is absolutely key. No question about it.
Sure its important, but i’m single and make 60,000 a year, to suggest i have the same portfolio size as you at age 50 is utterly ridiculous.
Thanks for your blog i enjoy all your articles and good luck on your retirement journey.
Thanks very much.
Yes, true, but it’s also a stretch for me to retire with $2M or $3M invested like many others might. I know plenty of folks that have done far better than me financially. I also know I’m ahead a bit of others. It doesn’t matter. Personal finance is all relative and very personal.
As long as you are meeting your goals, your objectives, on $60k or $600k per year, that’s all that matters.
I hope that provides some context and I appreciate the call outs.
Mark
Thanks Mark. Good advice to focus on your goals. I’m a little oversensitive I think. I just recently realized if i’m supposed to have 70% of what a couple has in retirement i should be saving more and its a little daunting. (I do have a pension that will help.) But this interaction reminds me that i should have a raise coming up and you are supposed to increase what you save when you get a raise so hopefully that will help!
All good, Christina, and yes – if you can find a way to “bank that raise” those types of things will really help!
Mark
How much cash?
Where I’m at today: When combined with regular income, such as, dividends. rent, and pensions, at least enough cash to cover three years of spending from the moment the markets dip by an amount where it starts to feel uncomfortable to be selling equities.
I recall reading, and I wish I could remember where, something along the lines of whatever the number is you’ve come up with for your cash bucket, it isn’t enough!
Sometimes everything goes to pieces at the same time, like today, and sometimes things don’t recover for six+ years. So, do you prepare for the short-lived crashes, average duration crashes, or worst case crashes? Is having cash sat around waiting for such a situation a lost opportunity? With hindsight following a booming market, absolutely, but if you’re reading this, how much money have you put into life insurance premiums (on your own life), and you’ve had zero return! Same goes for any insurance that you never claim on. Perhaps we should be looking at the cash bucket as an insurance policy, and have it just a little bigger than we at first thought it should be.
Just a few thoughts rattling around my head.
Great details.
Well, if assume dividends are guaranteed (not in my book), I will eventually have >$4k per month to spend. We’ll see 🙂
That said, I sleep better with cash in my bank account. I have no worries about spending $5k or $10k as needed on a moment’s notice.
Worse case, I can invest that money from time to time!
I see this cash wedge/larger cash cushion vs. my investments as more like a short-lived crash whereby I need money and do not want to spend a cent from my portfolio, dividends or otherwise. Meaning, I wouldn’t have to withdraw a cent from my portfolio for months if I didn’t need to do so.
Will that be ever needed? I have no idea 🙂 I hope not which is why I have the money just in case.
Hi Mark,
I was surprised to see that no one mentioned using their personal line of credit (secured against a home, so slightly lower interest rate) as an emergency fund. Assuming financial surprises are few and far between, you could have that 50K in cash invested and collecting dividend income, which hopefully would cover any interest you might pay while repaying the loan. If your lucky and never need the emergency fund, you are money ahead.
Howard
Interesting point, Howard. I think the challenge for some folks, is, with interest rates/borrowing costs going higher (as they should IMO – been way too low for way too long….), tapping LOC triggers more debt.
Certainly, if some folks are struggling with debt, now, and they have an emergency – should they really borrow more money?
Back to me, I think $50k will be plenty to start semi-retirement with. Maybe too much?
$50k invested would trigger, what, about $2k-$3k in dividends per year? Not bad really and I see your point in using that income stream to pay off the LOC.
What cash are you keeping on hand?
Mark
Howard, you’re making a lot of sense here. I understand this does not work for everyone, but as a DIY Dividend investor we have dividends to cover all expenses, and more. Why wait for an emergency that may or may not come? Use cash to compound your investments. When retired and in your own home a line of credit is all you need. I can’t remember a time when I needed to access my LOC for an emergency. I’ve used it to invest, to buy cars, any time I had a big expense. Then pay it off in short order with dividends. Now it just sits there just in case. That is the only emergency fund for me.
Very fair, DivInvestor!
Mark
Went into retirement with 2 years of living expenses in cash. Invested fully in market (2/3 XDV 1/3 CPD) with portfolio generating enough to replenish annual spending thereby (hopefully) keeping 2 years living expenses in perpetuity. While I believe a 1 year cushion, with adequate dividend flows to replenish would be sufficient, the 2 year cushion gives me (so I sleep soundly at night) 2 advantages. The first being using some of that 2nd year cushion to fund extra spending (if desired) which seems to come up in the early retirement years, without eating into your capital . Secondly, since your current dividend income will not be spent for 2 years, you have sufficient time to adjust your spending to any income shocks that may occur. Been retired now for 7 years and still have my 2 year cash cushion in place. Spent into cushion in early years for some additional travel but have replenished cushion through reduced spending in other years.
Terry, that’s impressive and well planned for your personal situation.
I think as we enter part-time work/semi-retirement, one year in cash savings should be enough but you never know!
I will consider going 2-years’ in cash/GICs like a more traditional cash wedge when full retirement occurs/not working at all.
I’m not sure when that might be, but full retirement could be 10 years from now.
I do appreciate the fact that when I turn off my DRIPs, the cash can accummulate and I can withdraw that cash for spending from my portfolio. Thoughts on that? Do you still DRIP your stocks or ETFs?
Mark
We let our dividends accumulate in the cash portion of our investment accounts replacing the cash we spend monthly (DRIP not used since we retired). Have not worried about the return on this cash to date, as interest rates have been so low for the last decade, but have been looking at short term rates lately.
Have found that our living expenses in retirement are much lower than before (excluding travel) or what the financial industry states. It surprised me how after several years of retirement my priorities changed. Our discretionary spending has changed considerable from our working days freeing up cash flow and reducing our total income needs. While we did spend more in the first few years of retirement we found we have settled into a comfortable and lower level of spending in general. I personally believed that once your income from investments/pensions exceeds your living expenses then further wealth accumulation is unnecessary from a financial standpoint.
If I could give one piece of advise to those contemplating work retirement is to try living for 1 year (tracking ALL spending) on what you believe you will require in retirement. Use this information to make an informed decision on your retirement plan and adjust accordingly. If everything works out now your only question is when to pull the plug.
Have always found your blog very informative in a common sense approach to retirement planning.
Thanks for the kind words, Terry.
That sounds like my plan, a bit?
1. RRSPs = stop DRIPs in my/our 50s and basically spend the dividends and distributions from the accounts each year/withdraw the cash. This means RRSPs/RRIFs will be depleted in my/our 70s.
2. Non-reg. investment accounts = stop DRIPs in my/our 50s and basically spend the dividends and distributions from the accounts each year/withdraw the cash. Slowly sell the stocks in taxable over decades.
3. Leaving TFSAs intact until my 70s or 80s.
You: “Have found that our living expenses in retirement are much lower than before (excluding travel) or what the financial industry states. It surprised me how after several years of retirement my priorities changed. Our discretionary spending has changed considerable from our working days freeing up cash flow and reducing our total income needs.”
Very interesting…I have a budget spreadsheet to know what we need, now, and basic expenses (food, shelter, transportation) equate to about $4,000 or so per month. Fun, entertainment and travel will be another $2k or so per month.
I figure any target spend of about $6,000 per month, on average, in retirement, will be very good. If I can “live off dividends and distributions” in retirement, first 5 years, with the portfolio churning out $6k per month (excluding CPP, excluding OAS, etc.) then I know my wife and I will be more than fine without any debt on the books.
I’ve learned/continue to learn from others that:
You: “I personally believed that once your income from investments/pensions exceeds your living expenses then further wealth accumulation is unnecessary from a financial standpoint.”
Love it.
Mark
Terry,
I also allow the dividends to mount up prior to pulling them out in December, but I buy Horizon’s High Interest ETF (CASH.TO) each month. I earn interest that is greater than the transaction fee (in Questrade there’s only a sell fee). Better than the cash doing absolutely nothing.
Dear Mark,
I am a senior whose husband recently died, and “my” income will be quite dramatically reduced. I am grateful for my significant cash wedge which has spared me at least money anxiety as I deal with paperwork delays over his reduced pension income.
I was the one interested in investing, and I made all the mistakes one could, but some of them were mistakes I’m okay with. Despite my extreme home bias, triggered by my earlier loses in a US mutual fund, I have made “enough” in investments. Another person would be frustrated by the money I’ve left on the table. Some of us are biased towards sleep well at night, and others towards not leaving money on the table. An investor’s personality plays a huge role in what’ s best for them.
I am a long term reader and enjoy your blog. I suspect I am inclined towards a “what I think myself” bias, much like a home country bias. Thanks for the enjoyable reads.
Sharon, I am very sorry for your loss. My condolences.
On the investing side, I suspect your cash wedge has served you well and seems very smart in hindsight. Kudos for that level of catastrophe planning.
I too have made a number of investing mistakes. I’m simply trying to limit them as I move along my journey. I suspect we don’t learn unless we make a few mistakes in life along the way…
I fully appreciate the sleep-at-night factor. I know I feel better with some cash savings in the bank to go along with my dividend income and low-cost ETF journey. I’m far from perfect when it comes to investing but I figure if I can continue to do a number of good things right, that’s all I need.
Best wishes to you and thanks for your readership Sharon. Stay well.
Mark
Good topic with well thought out options for yourself and for others to consider. Its very personal and probably varies a lot by person and all circumstances, needs etc.
We have about a years spending worth in a HISA for easy accessibility, and about another 9-10 years of spending in FI accessible both if we didn’t want to rely on dividends/distribution for income, or to reinvest that, or finally to rebalance if markets dropped significantly.
Wow, that’s great. I have a new post out today about bonds. I look forward to your comments 🙂
Funny on that timing!
Ha, just posted 🙂
https://www.myownadvisor.ca/why-would-anyone-own-bonds-now/
I look forward to your reply.
That’s impressive: “We have about a years spending worth in a HISA for easy accessibility, and about another 9-10 years of spending in FI accessible…”
I figure once any/all dividends and distributions cover basic expenses (excluding CPP, excluding OAS and excluding any TFSA withdrawals) that should be “enough” as we work part-time. The real question for us will be when we stop working even part-time. I suspect we’ll want a bit more of a cushion.
Thanks. It’s not for everyone but so far is ok for us. There is a financial cost to it. Ideally I’d continue on our current path and bring that FI down by a years worth each year until CPP (~7+ yrs) by spending from it, and then hold maybe ~2-3 yrs worth of FI/cash at age 70+. Loosely my plan.
Great plan Mark. I agree.
I believe you’ll know when is the right time to stop work. I was always highly motivated for work and I felt that wane a bit from 100% and decided right then for my employer, customer and myself it was best to call it a day. I had been earning a lot more even working PT then than before, so it took thought to leave.
I suspect you will too. I believe the hardest thing you’ll face in semi or full retirement by far is letting go and spending even remotely close to your possibility. Switching to that after being so focused on accumulating will be tough and I think you’ll want to build that pile for a long time! But maybe you want that.
Should CPP and OAS and some pension almost cover all expenses (at ages 70+), and then you have your portfolio value by which you can live off 2-3% withdrawals if necessary for life (i.e., the ETF or stock distributions), then I don’t see the need of keeping a decade or more worth of FI.
A couple of years (2-3 years), for sure in cash or with GICs but not more.
It will be interesting to see how my views will change with time. I remain motivated by work and I enjoy my current team. I have a feeling I know when the time will be right! 🙂
You may find that your need for a huge chunk of cash changes over time. When I first stopped working fulltime, I kept 2 years of expenses in cash plus had a lot of bonds. Now, 2 decades later and fully retired, I have about 4-6 months of expenses in cash– mostly to smooth out the lumpy dividends that I live off, and zero bonds. So your comfort factor may increase over time as you get used to living primarily off your investments, reducing your need for “sense of security cash”
That’s some great perspectives Ed. I’m going with 1-year to enter semi-retirement with – other than that – 100% equities across my portfolio. Maybe too risky for some but if I’m still working that’s a good buffer I think. I will know more in a few years! 🙂
Happy New Year!
Thank you for re-posting this article Mark, very useful! All the best to you and your family in the new year!
Glad it helped! Again, just my plan and I’m also trying to align my ETF % up to about 50% at the start of semi-retirement in a few years.
Happy New Year back!
Most financial experts end up suggesting you need a cash stash equal to six months of expenses: If you need $5,000 to survive every month, save $30,000.
Ya, I don’t mind that number but I think in retirement because you can’t easily increase your income, I’m planning to keep about one years’ worth to start semi-retirement with. That’s about $50K for us.
Considering the current market retreat you should have sold all your sharesa month ago and be 100% cash now so you can pick up the bargains.
Nothing like 20/20 hindsight
RICARDO
LOL. Not that smart 🙂
Mark, we use Oaken Financial for our GICs.
We have numerous 1-year $5K TFSA and RRSP GICs (rolling terms). Their maturity dates are spread throughout the year. The GICs are intended as backup vs the planned source of income. If the markets are up/healthy around November/December I’ll sell units of the equity ETFs. If the values have crashed, I’ll sell some units of the ZAG ETF and/or cash out the GICs as they mature.
I gave up on maximizing my dividend income a few years ago as it was way too distracting for me – I‘m bad enough as it is now with just four ETFs + some funds overseas. After five years of daily fiddling with my 21 sheet spreadsheet, I’m just about finished. I almost can’t think of anything else to add.
“I gave up on maximizing my dividend income a few years ago as it was way too distracting for me – I‘m bad enough as it is now with just four ETFs + some funds overseas.”
Ya, I hear ya. With 40 stocks to track, I have to keep on top of things a bit but then again, I own the top stocks in a few big ETFs so I simply ride large-cap returns over time.
You seem to have things well in hand Bob with your GICs and planned source of income when you need it. Smart for times like these 🙂
Well, well, well it’s finally happening. I wish I was still in the saving mode — lots of good deals out there people — grab some everyone!
Indeed Gary, lots of good deals and maybe next week will bring better deals no one knows 🙂
this is my second experiment with a drop in the market , in 2008 i didn’t even know what’s bonds and what’s stocks but i just listened to one of the teller at my bank and started investing in mutual funds in my rrsp and the whole roller coaster ride went smoothly today in 2020 I’m following a ccp portfolio and thank God to my 40% Bonds in my portfolio that smoothing the ride and i finally got to test how those boring bonds acts like a safety nets 🙂
but yeah i agree i think we’re having a black friday sale in February this year .
Yes, a second drop but let’s remember we’re just at October 2019 levels 🙂
We have a LONG way to go before any significant market calamity.
That said, Gus, you’re wise to follow a lazy ETF portfolio approach and ride this out. 40% bonds will absolutely help that and you don’t invest in bonds for big returns, simply, times like these.
I hope to buy some more assets in a few weeks once I have more money to invest via 1st of month RRSP contributions.
Happy investing!
welcome back Mark ! Glad you had fun in Belize ( it’s on my list for retirement 🙂
Thanks for putting the tiny pullback it in this perspective i didn’t think about it this way but seeing the chart made it a lot easier and October 2019 wasn’t that bad at all 🙂
and yes it was a good test for my balance portfolio so i slept well at night, but I have a bit of cash that i want to add to my etfs but I’m not sure to when do i buy do i wait for Monday and see if the market is still going down ? would that be timing the market ? but then if it’s still coming down why not wait for it ? haha it’s a bit confusing for me i never bought those dips i usually stay put i guess no buying or selling so this is new for me 🙂
Yes, I mean, unless we get to 2010 levels not too worried. As long as they don’t cut any dividends on me, I’ll be happy! You never know!
I’m going to wait another week to buy some ETFs or stocks myself. I need to let my monthly RRSP contributions happen first.
Otherwise, staying boring here Gus.
Mark
I hope I can Gary!
Your recommendations for $500,000 inside buckets 2 and 3 by age 50 are extremely unrealistic for most people. Your bucket totals over $1,000,000 by age 50! No way Jose!
That’s a fair point Joseph but I’ve also been at investing for 20 years now and I should be at where I can with my diligent approach.
Those folks that have not saved over 20 years like I have, diligently, certainly won’t have this portfolio value. It does take time and effort!
Hi, we keep approx 8-12 months of cash in our RRSP to either pay for living expenses or deployed if a buying opportunity arises. This amount is largely untouched at this point (we are late 50s) but can be withdrawn and then taxes paid if required. Otherwise we normally supplement our income with the dividends from our non-reg account.
Very smart Peter. I probably only keep a few thousand at any point in time. I prefer to have nearly all of my money invested as much as possible.
That said, I hope to start increasing our cash wedge beyond current emergency fund approaching that $50k in 2021 sometime.
Thoughts on that? Seems almost aligned with your 8-12 months for future purchases…albeit different account(s).
Mark
Well, we are fortunate that the 8-12 month “reserve” only accounts for approx 4% of total portfolio (maybe more like 5 or 6 after this week?! haha).
We stopped automatic dividend re-investments about 3 yrs ago to build up a cash reserve, so most of that is dividends that have been paid but not cashed out of our accounts, therefore tax protected/deferred.
That makes sense. I’m not sure when I will “turn off” my DRIPs inside my RRSP and TFSA but I suspect once we’re in semi-retirement and we want to spend the dividends and distributions, that will be the time.
Actually, thinking about it more, will likely turn off DRIPs inside RRSP before TFSA. I’ll keep the stocks DRIPping inside the TFSA for as long as I can 🙂
Mark
That’s exactly what we did. We were DRIPing all along and then when my wife retired, we stopped them to build up this cash reserve. This was only done for our RRSPs, the TFSAs just keep rolling along and will be the “last money out of our portfolio”, sometime in 2055 or thereabouts haha
Sounds like a great plan to mimic. We intend to keep TFSA DRIPping “until the end” and use our RRSP dividend + distributions for cash flow/expenses along with our non-reg. account to pay for expenses in the early 10-20 years of retirement.
Hoping the combination of RRSP withdrawals + non-reg. should cover most expenses (condo fees, taxes, groceries, etc.). Potentially some part-time work can cover our international travel.
Cheers Peter, keep me posted on any deals next week. I’m looking at MSFT and the low-cost ETF ITOT myself.
Quote: “What I mean is, our rule of thumb is $30k invested, creates $1k of dividend income. So you can quickly figure out how much you need invested to cover your yearly costs”
That rule may apply to “Purchases”, but by investing for Income I find that your Yield on invested dollars increases over time. The result is that your income will grow and your yield will rise or you will receive more income for less money invested.
True, it should Cannew. Just remember the yield on cost perspective applies to funds and other assets as well.
Back from vacation and will be looking at doing our post together later this month (March).
Cheers!
Mark
We recently concluded that we have enough (or will have in a few months) so we don’t need to strive for gains much over inflation. With this new mindset, we are pivoting to having five years worth of fixed income. The mix is 50% bonds (ZAG), 20% cash, and 30% GICs. On the cash and GICs, I actively seek out the best rates.
I have two plans in my spreadsheet; Plan A assumes a normal market as we go into retirement, and Plan B assumes a near total market meltdown the day I retire. Seeing a hint of a major market downturn over the coronaviris outbreak, I feel comfortable having Plan B.
I forgot to mention that our five years worth of fixed income includes dividend income.
I think you’re in a great place then Bob with that much fixed income as a buffer.
Very well done.
Mark
I think I know of other retirees/investors/near-retirees that are liking ZAG for fixed income as well. Seems like a popular BMO product for many.
The cash is smart. What GICs do you use? A ladder? Or do you do 1-year rolling terms? Curious since I might get my parents set up in something for them on that note.
I keep my dividend income spreadsheet updated fairly regularly. I like seeing how the income earned is approaching > expenses. Once we reach our “crossover point” (dividend income + distribution income from all invested assets > expenses) then my wife and I will consider working part-time (assuming no debt of course). I figure that’s a good strategy for us and should be aligned to your plan B.
Mark
It looks very much like I’ll be implementing “Plan B”!
It was painful watching stocks climb higher and higher while I was building up my cash cushion. I’m glad I did.
I think this is an outstanding reminder to highlight keeping some cash is always very prudent. I wish I had more myself but I’m working on my plan!
2 questions….
1) “1. I think any money you absolutely need/absolutely depend on in the next 1-2 years should likely be in cash or some form of fixed income”. Can that “fixed income” include an amount I would receive from an employer pension or CPP? I am in my very early 50s and my very small work pension is something I can access as soon as I leave work. Can I deduct the amount I will be receiving from that from the amount of cash I need to have? Can I reduce the amount of the cash buffer when I turn 60 and start to receive CPP?
2) Can I withdraw the dividends from my RRSP monthly and use them to replenish the cash wedge? I know that less tax will be withheld from the bank if I withdraw them in smaller amounts. 10% withholding for amounts less than $5,000 and 20% for amounts over that. I will be a low income retiree and I want to keep all withdrawals from my RRSP, which count as income, steady throughout the years to minimize my taxes.
Absolutely. A broader definition of fixed income in my book is anything that is pension-like and therefore dependable, that could be a workplace pension, CPP, OAS, other. Consider an investor who needs and wants to spend ~ $50,000 after-tax in retirement and has $40,000 pension + $10,000 CPP benefits per year + $6,000 OAS benefits per year. In addition, they have considerable RRSP assets. Maybe this investor does need to have a major cash fund because so much of their money is highly dependable/not going to be comprised.
It really depends. Personally, we have decided ~ $50,000 in cash acting as an emergency fund/cash wedge for a 12-month of so very bad series of events or stock market returns should be enough for us.
Regarding 2), yes, I know of some retirees that are withdrawing from their RRSP now, spending some RRSP money now and using leftover $$ not spent to fund their TFSA every year and/or increase their cash wedge/savings and put that money in secure investments such as a GIC ladder. There is no need to always spend your RRSP withdrawals completely!
“I want to keep all withdrawals from my RRSP, which count as income, steady throughout the years to minimize my taxes.” Smart work 🙂